
Nov 16, 2026 · @Hans Scheil
By Hans Scheil, CFP®, CLU®, ChFC®, CASL®, CLTC®
I hear the same words from clients in their 60s and 70s almost every week: “I don’t need life insurance anymore.” The house is paid off. The kids are grown. The term policy they bought 30 years ago is about to expire, and they’re happy to let it go.
Sometimes they’re right. Not everyone in retirement needs life insurance, and I don’t recommend it for everyone. But in more than 40 years in this business, I’ve noticed something. I have never had a beneficiary tell me they wished their mom or dad hadn’t bought a policy. Not once. When that check arrives, it is always welcome.
A decision that gets harder to reverse
Letting coverage lapse is easy. Getting it back is not. Every year you wait, premiums go up, and a single health diagnosis can make a new policy expensive or impossible to buy.
That’s why I ask clients to change the question. Instead of “Do I need life insurance?” I ask, “What do I want the people I leave behind to deal with?”
When we run a full financial plan, we test different scenarios. What if long-term care uses up most of your savings? What if one spouse dies 15 years earlier than expected? In many of those scenarios, a need appears that wasn’t obvious at first. And sometimes it isn’t a need at all. It’s simply something the client wants for their family.
The three types of policies we use for people in their 60s and 70s
Most of the planning we do for this age group uses one of three kinds of coverage. Which one fits depends on how long you need it and what you want it to do.
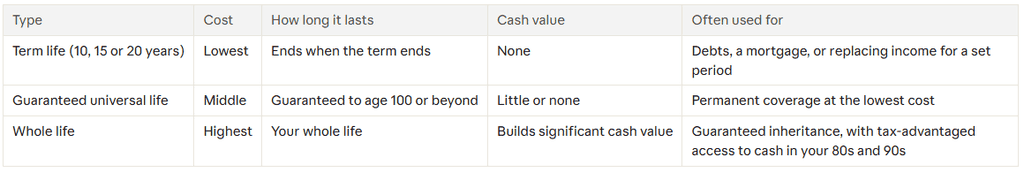
With whole life, you can also choose to pay the policy off in 10 years. That way the premiums end while you’re still in your 70s.
Reasons that apply whether you’re single or married
Final expenses and estate settlement. Even a $25,000 to $50,000 policy puts cash directly in the hands of whoever is handling your affairs. Your executor needs money to pay the funeral home, the lawyers and the bills on your property, often before your other assets can be sold or retitled.
Outstanding debt. A term policy can cover a mortgage, car loan or credit card balance for the next 10 or 15 years, so those debts don’t fall on your family.
A guaranteed inheritance. We recently worked with a couple who wanted to leave $1 million to their children. Their plan was to never spend below that amount. We flipped it around. They now pay for a whole life policy over 10 years using withdrawals from their IRA, which they would have been taxed on anyway. The $1 million is guaranteed, goes to their kids income-tax-free, and avoids probate. Now they’re free to enjoy the rest of their savings.
Supporting an adult child or grandchild. Several of our clients have children with special needs who are in their 30s and still live at home. Their biggest worry is who will care for that child when they’re gone. A whole life policy that pays into a special needs trust brings money in quickly, right when it’s needed.
Charitable giving. One of our clients passed away unexpectedly and left his wife a $200,000 policy. Once we confirmed she would be financially secure, she used the money to buy a new organ for their church. It was a goal the two of them had been saving toward for years.
Long-term care protection. Many of the policies we place today are hybrids. If you need long-term care, the policy helps pay for it. If you never do, your beneficiaries get a death benefit that’s generally at least what you paid in.
The part couples forget: what happens to the survivor’s income
When the first spouse dies, the household loses a Social Security check. The survivor keeps the larger of the two, and the smaller one stops. If there’s a pension with no survivor benefit, that stops too.
The bills don’t drop by half. The survivor still pays for the same house, the same car insurance and the same utilities.
One couple we work with shows how big the gap can be. The husband, a veteran, receives a tax-free military disability pension of about $50,000 a year that ends at his death. If he dies first, his wife’s income could drop by about 70%. A life insurance policy is how we close that gap.
Other situations where married couples turn to life insurance:
- Pension maximization. Take the larger single-life pension, and use part of the extra income to buy a policy that pays your spouse income-tax-free.
- Protecting a younger spouse. One client is still working in his 70s, and his wife is in her early 60s. A 10-year term policy replaces his paycheck if he dies before 80.
- Keeping the home. Many people in their 60s and 70s still have a mortgage. A term policy can pay it off at the first death.
- Blended families. In second marriages, the 401(k) often lists the children from the first marriage as beneficiaries, which can leave the surviving spouse short. A modest policy on each spouse, with the children as beneficiaries, lets the other assets go to the surviving spouse. It works in reverse, too.
- Survivorship (second-to-die) policies. These pay when the second spouse dies and cost less than covering each spouse alone. They can guarantee an inheritance or pay estate taxes. The federal exemption is $15 million per person, but many states set their own estate or inheritance taxes much lower.
If you’re single, someone else carries the load
Without a spouse, there is no one to absorb the final costs and paperwork. My colleague Drew Sumallo saw this firsthand. A relative of his aunt died without life insurance and asked to be buried in his home country. His aunt, as executor, had to arrange and pay for the transport and burial, much of it out of her own pocket. It took her months to sort it all out. A $25,000 policy would have made a hard time much easier.
Single clients also use life insurance to:
- Provide for a partner they aren’t married to, quickly and simply, by naming them as beneficiary
- Keep supporting aging parents, siblings, nieces or nephews who depend on them
- Leave a defined legacy, like one client who funds a policy so her niece is guaranteed a check, while she can still reach the cash value if she ever needs it
If health or age rules out a policy, there are other options. An annuity with no health questions and a named beneficiary can serve a similar purpose for final expenses.
3 steps to take this week
- Check your current policies before they lapse. Find out when any term coverage ends, and whether it can be converted to permanent coverage without a new medical exam.
- Write down what stops at the first death. List each Social Security and pension check in your household, and mark which ones end or shrink when a spouse dies. Compare what’s left to your actual monthly bills.
- Review every beneficiary designation. Look at your life insurance, 401(k)s, IRAs and annuities. Make sure each one still matches what you want, especially if you’ve remarried.
Make the decision with the whole picture
Life insurance is sometimes oversold, and I’m not suggesting you put all your money into it. But writing it off without a second thought is the opposite mistake. Look at it as one part of your overall plan, alongside your income, Social Security, long-term care, taxes and estate plan.
Tom Griffith, Drew Sumallo and I walk through all of these situations in our latest video, “Why Do People Buy Life Insurance in Their 60s and 70s?” You’ll find it, along with free show notes, at CardinalGuide.com, or call us at 919-535-8261.
Guarantees are based on the claims-paying ability of the issuing insurance company. This article is for general information only and is not tax or legal advice. Consult your tax or legal professional about your situation.


